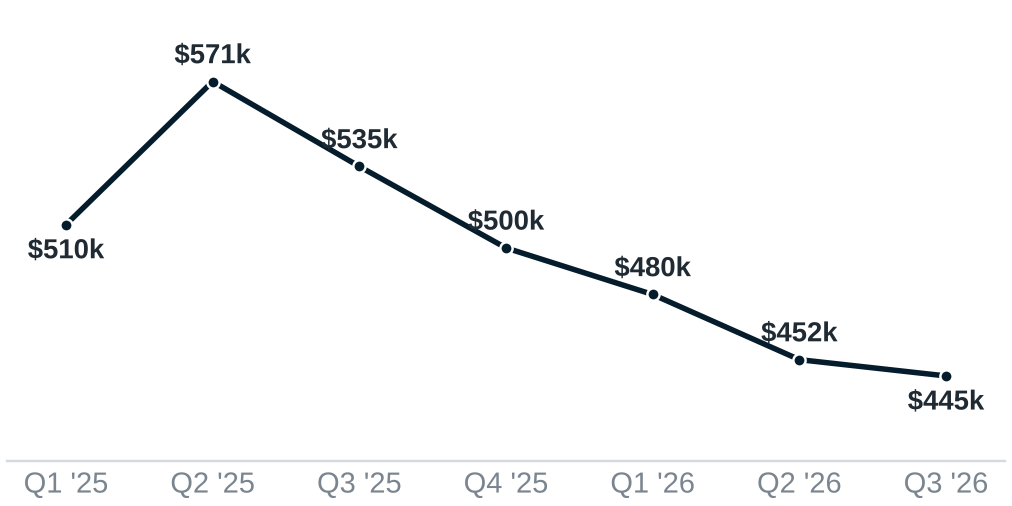
The CBD apartment market found steadier footing through the September quarter. The median sale price settled at $445,000, close to June’s $452,000 after a year of gradual easing — and the bedroom-level numbers are steadier still: one-bedroom apartments traded at a median of $355,000, in line with a year ago. Where the CBD is unambiguously strong is rentals. Listings are leasing in around half the time they took a year ago, and the city continues to offer some of the highest gross yields in inner Melbourne.
- Median sale price of $445,000 in Q3 2026, down just 1.5% on the June quarter — the smallest quarterly move in a year.
- Most of the gap to a year ago ($535,000) reflects mix rather than value: fewer large three-bedroom sales this year, while one-bedroom medians moved from $350,000 to $355,000.
- Three in four sales (74%) fell in the $350,000–$850,000 bracket — the CBD remains overwhelmingly a one- and two-bedroom market.
- Rentals leased in a median 15 days this quarter, down from 29 days a year earlier, with one-bedroom asking rents up 8.5% to $575 per week.
| Metric | Melbourne CBD (3000) |
|---|---|
| Market Trend | Flattening after a year of easing |
| Buyer Demand | Moderate — buyers taking their time |
| Rental Demand | Very Strong |
Gross rental yields across the CBD range from around 7.2% on three-bedroom apartments up to approximately 8.4% on one-bedroom stock — among the strongest cash returns available anywhere in inner Melbourne.
Top 10 sales, Q3 2026
| Address | Price | Beds | Bath | Car |
|---|---|---|---|---|
| 2601/17 Spring Street | $6,600,000 | 3 | 3 | 3 |
| 6503/371 Little Lonsdale Street | $5,400,000 | 3 | 3 | 2 |
| 2805/433 Collins Street | $1,580,000 | 2 | 2 | 1 |
| 3/165 Flinders Lane | $1,425,000 | 1 | 1 | — |
| 1706/333 Exhibition Street | $1,325,000 | 3 | 2 | 1 |
| 3601/299 King Street | $1,100,000 | 2 | 2 | — |
| 5412A/560 Lonsdale Street | $1,028,000 | 3 | 2 | 1 |
| 1004/118 Russell Street | $1,020,000 | 2 | 2 | 1 |
| 143/283 Spring Street | $941,000 | 3 | 2 | 1 |
| 1001/31 Spring Street | $888,000 | 2 | 1 | 1 |
Source: PriceFinder Sales Search, Melbourne VIC 3000. Sales dated July–September 2026 with price disclosed, as reported at 2 October 2026; excludes sales without bed/bath data and one agent-advised record pending verification. Dashes indicate car-park data not captured for that title. For a full property report on any of these sales, contact Mark directly.
Market comment
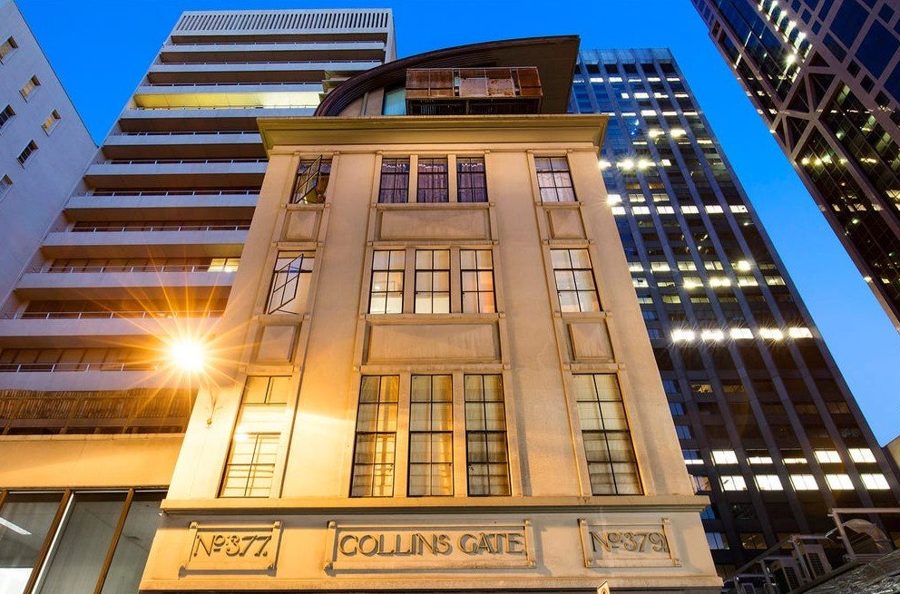
The quarter’s top end was led by a $6.6 million three-bedroom result at 17 Spring Street, ahead of a $5.4 million three-bedroom sky home at 371 Little Lonsdale Street. Spring Street featured three times in the top ten, a reminder that the city’s leafy eastern edge remains its prestige address. Below the top tier, the CBD is a different market altogether: the middle of the market sits under $500,000, and one- and two-bedroom apartments account for nearly every sale. That split matters for owners — the premium end and the investor-grade towers are pricing off very different buyers.
Market activity
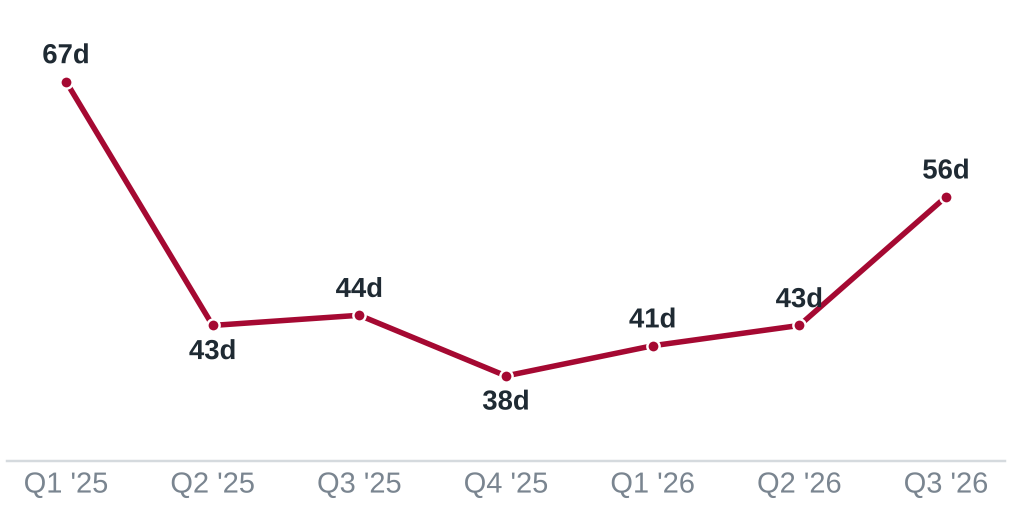
The CBD’s median sale price has eased from a peak of $571,500 in Q2 2025 to $445,000 this quarter, but the pace of that decline has slowed sharply — Q3 sat just 1.5% below Q2. Typical time-to-sell lengthened to 56 days, up from 43 in the June quarter: prices are holding, but buyers are in no hurry and are negotiating.
By bedroom count, one-bedroom apartments posted a Q3 median of $355,000 and two-bedroom apartments $500,000 (from $524,500 a year ago), while the smaller three-bedroom segment cleared $790,000. Sales were most concentrated on Lonsdale Street, A’Beckett Street, Collins Street and Elizabeth Street.
With one-bedroom prices broadly flat at around $355,000 and asking rents up 8.5% year on year to $575 a week, the gross yield on a typical CBD one-bedroom apartment has lifted to 8.4%, from 7.9% a year ago. Two-bedroom yields have moved the same way, from 7.1% to 7.8%.
Rental market
Rental conditions tightened markedly over the past year. The median listing leased in 15 days this quarter, compared with 29 days in Q3 2025. Asking rents rose through late 2025 and have held since: two-bedroom apartments — the most common stock — sit at $750 per week (from $715 a year ago), and one-bedroom apartments at $575 (from $530).
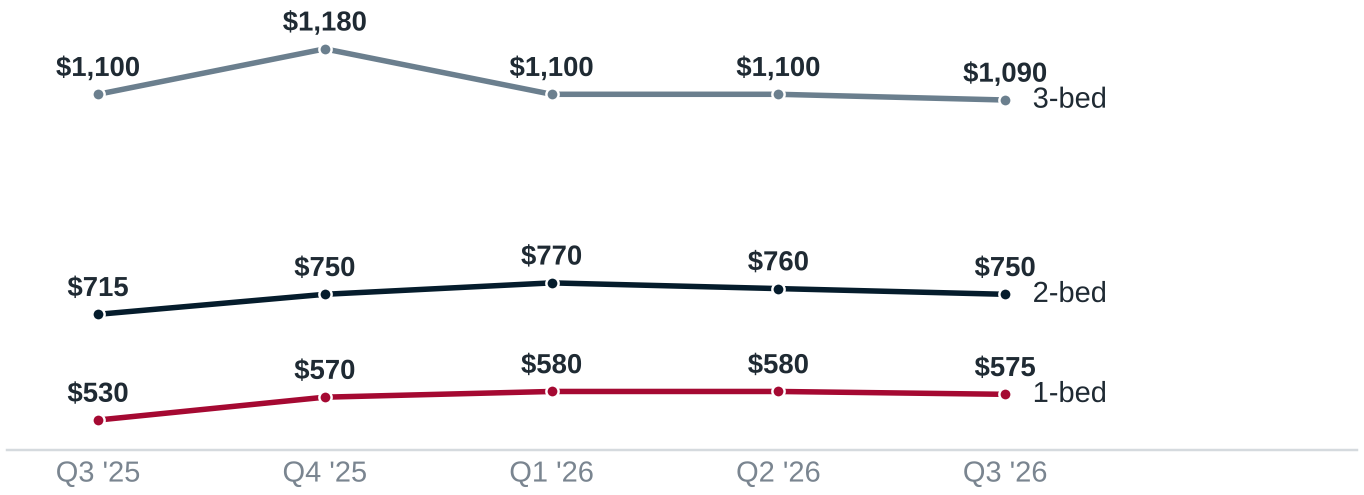
Measured against current sale prices, that puts gross rental yields at roughly 8.4% for one-bedroom apartments, 7.8% for two-bedroom apartments and 7.2% for three-bedroom apartments — the CBD remains one of the clearest cash-flow plays in the inner city.
Get your personalised value report in a few easy clicks, delivered to your email. Free & easy!
Community — what’s on in October
Independent theatre, comedy and performance across the city, with hubs at Trades Hall and Fed Square — including a free daily fire-pit installation, Dhandha/Campfire, at Fed Square.
Video games, tabletop and esports at ACMI, Fed Square and the Melbourne Convention and Exhibition Centre, with PAX Aus running 9–11 October.
Free opening-weekend program at Fed Square, including a Rebirth Brass Band second-line street party on Saturday 17 October from 1pm. Festival runs to 25 October.
Runway shows and designer showcases at venues across the city.
Dates as published by organisers at 2 October 2026 — check event websites before attending.
Figures are medians from PriceFinder sales and rental listing data for the Melbourne CBD (postcode 3000), July–September 2026, with information cut off 2 October 2026. Gross yield = median weekly asking rent × 52 ÷ median sale price, same quarter and bedroom count. Dingle Partners operates six inner-city offices — for a free appraisal of your property, get in touch.