Published September 2026 | Dingle Partners — Melbourne’s Inner-City Property Specialists
There is a narrative of the 2026 Melbourne property market correction that looks orderly and even: A broad softening across all price points, driven by the same set of interest rate pressures affecting every buyer equally. The actual data published this week tells a considerably more interesting story.
Cotality’s September housing analysis shows that homes in the top 25% of Melbourne’s market have fallen 10.5% from their peak, with a median value of approximately $1.2 million. Homes in the lower quartile, by contrast, are down less than 4%. The gap between the high-end and more affordable stock is more than 6% – not a minor variation. The market correction is applying different pressures to specific price segments: Two separate corrections running simultaneously, creating a tale of two markets.
Understanding which correction applies to your property, and why, is more useful right now than any single headline figure about Melbourne’s overall performance.
What the data actually shows
The segmentation is sharpest for detached houses. Melbourne’s upper-quartile houses have a current median of approximately $1.25 million, and their decline began in October 2025 — meaning the premium end of the market has been softening for nearly a year. The lower quartile of homes has followed, but at roughly half the pace and with considerably less momentum.
The unit market shows the same pattern but with an important difference in degree. The gap between upper and lower value unit declines in Melbourne is 4.9 percentage points. While substantial, this is considerably narrower than the equivalent gap in the detached housing market. Units have generally proven more resilient throughout the downturn, with resilience most pronounced in affordable homes.
One further data point worth holding: housing affordability has fallen to its lowest recorded level, with households earning a typical income only able to afford around one in every ten properties sold in the last financial year. That figure sits beneath the segmentation data and helps explain why it looks the way it does.
The primary driver: The affordability cascade
When interest rates rise, borrowing capacity falls — but the reduction is not uniform across the market. It bites harder, in dollar terms, at higher price points.
A buyer whose borrowing capacity has fallen by $300,000 may no longer qualify for a $1.5 million house. They do not exit the market entirely. They redirect their purchase to a $1.1 million house or to a well-located apartment in a suburb they would previously have bypassed. That movement concentrates demand in the mid-market and affordable segment, simultaneously withdrawing it from the premium tier. The result is exactly the pattern the data is showing: relative resilience at the affordable end and mounting pressure at the top.
APRA’s serviceability buffer — which requires lenders to stress-test borrowers at three percentage points above the offered rate — amplifies this effect significantly. The buffer applied to a $1.5 million loan is a very different number to the buffer applied to a $600,000 loan, and it filters out a much larger share of prospective buyers at the premium end of the market.
The first home buyer scheme cap of $950,000 in Melbourne is also creating a natural demand anchor at the affordable end — buying activity remains robust for properties sitting below that threshold. Premium properties have no equivalent structural support mechanism.
The secondary driver: strategic waiting at the top end
The affordability cascade explains most of the segmentation, but a second force is operating alongside it. Discretionary buyers at the premium end of the market can afford to wait in a way that most buyers cannot. And in a market where a $1.2 million median has fallen 10.5% from peak with the rate outlook still uncertain, waiting for a better entry point is a rational strategy rather than a sentimental one.
As Cotality notes, “elite buyers can delay purchases in a way ordinary buyers cannot” — a dynamic that has suppressed transaction volumes and clearance rates at the premium end considerably more than price data alone captures.
This second driver matters for understanding the shape of the fall at the top end. Cascading demand from buyers pushed down from higher price points explains most of the structural pressure on premium values. But the withdrawal of discretionary buying adds a sentiment overlay that deepens and extends the correction beyond what affordability alone would produce. The combination — fewer buyers qualified to purchase at premium prices, and those who are qualified choosing to wait — is what produces a 10%+ fall rather than a 4-5% one.
Where Melbourne’s inner-city market sits in this picture
The segmentation data is most useful for Melbourne buyers and sellers when it is read at the asset-type level rather than the city level — and at that level, the inner-city apartment market is sitting in a categorically different position to the premium house market that is leading the correction.
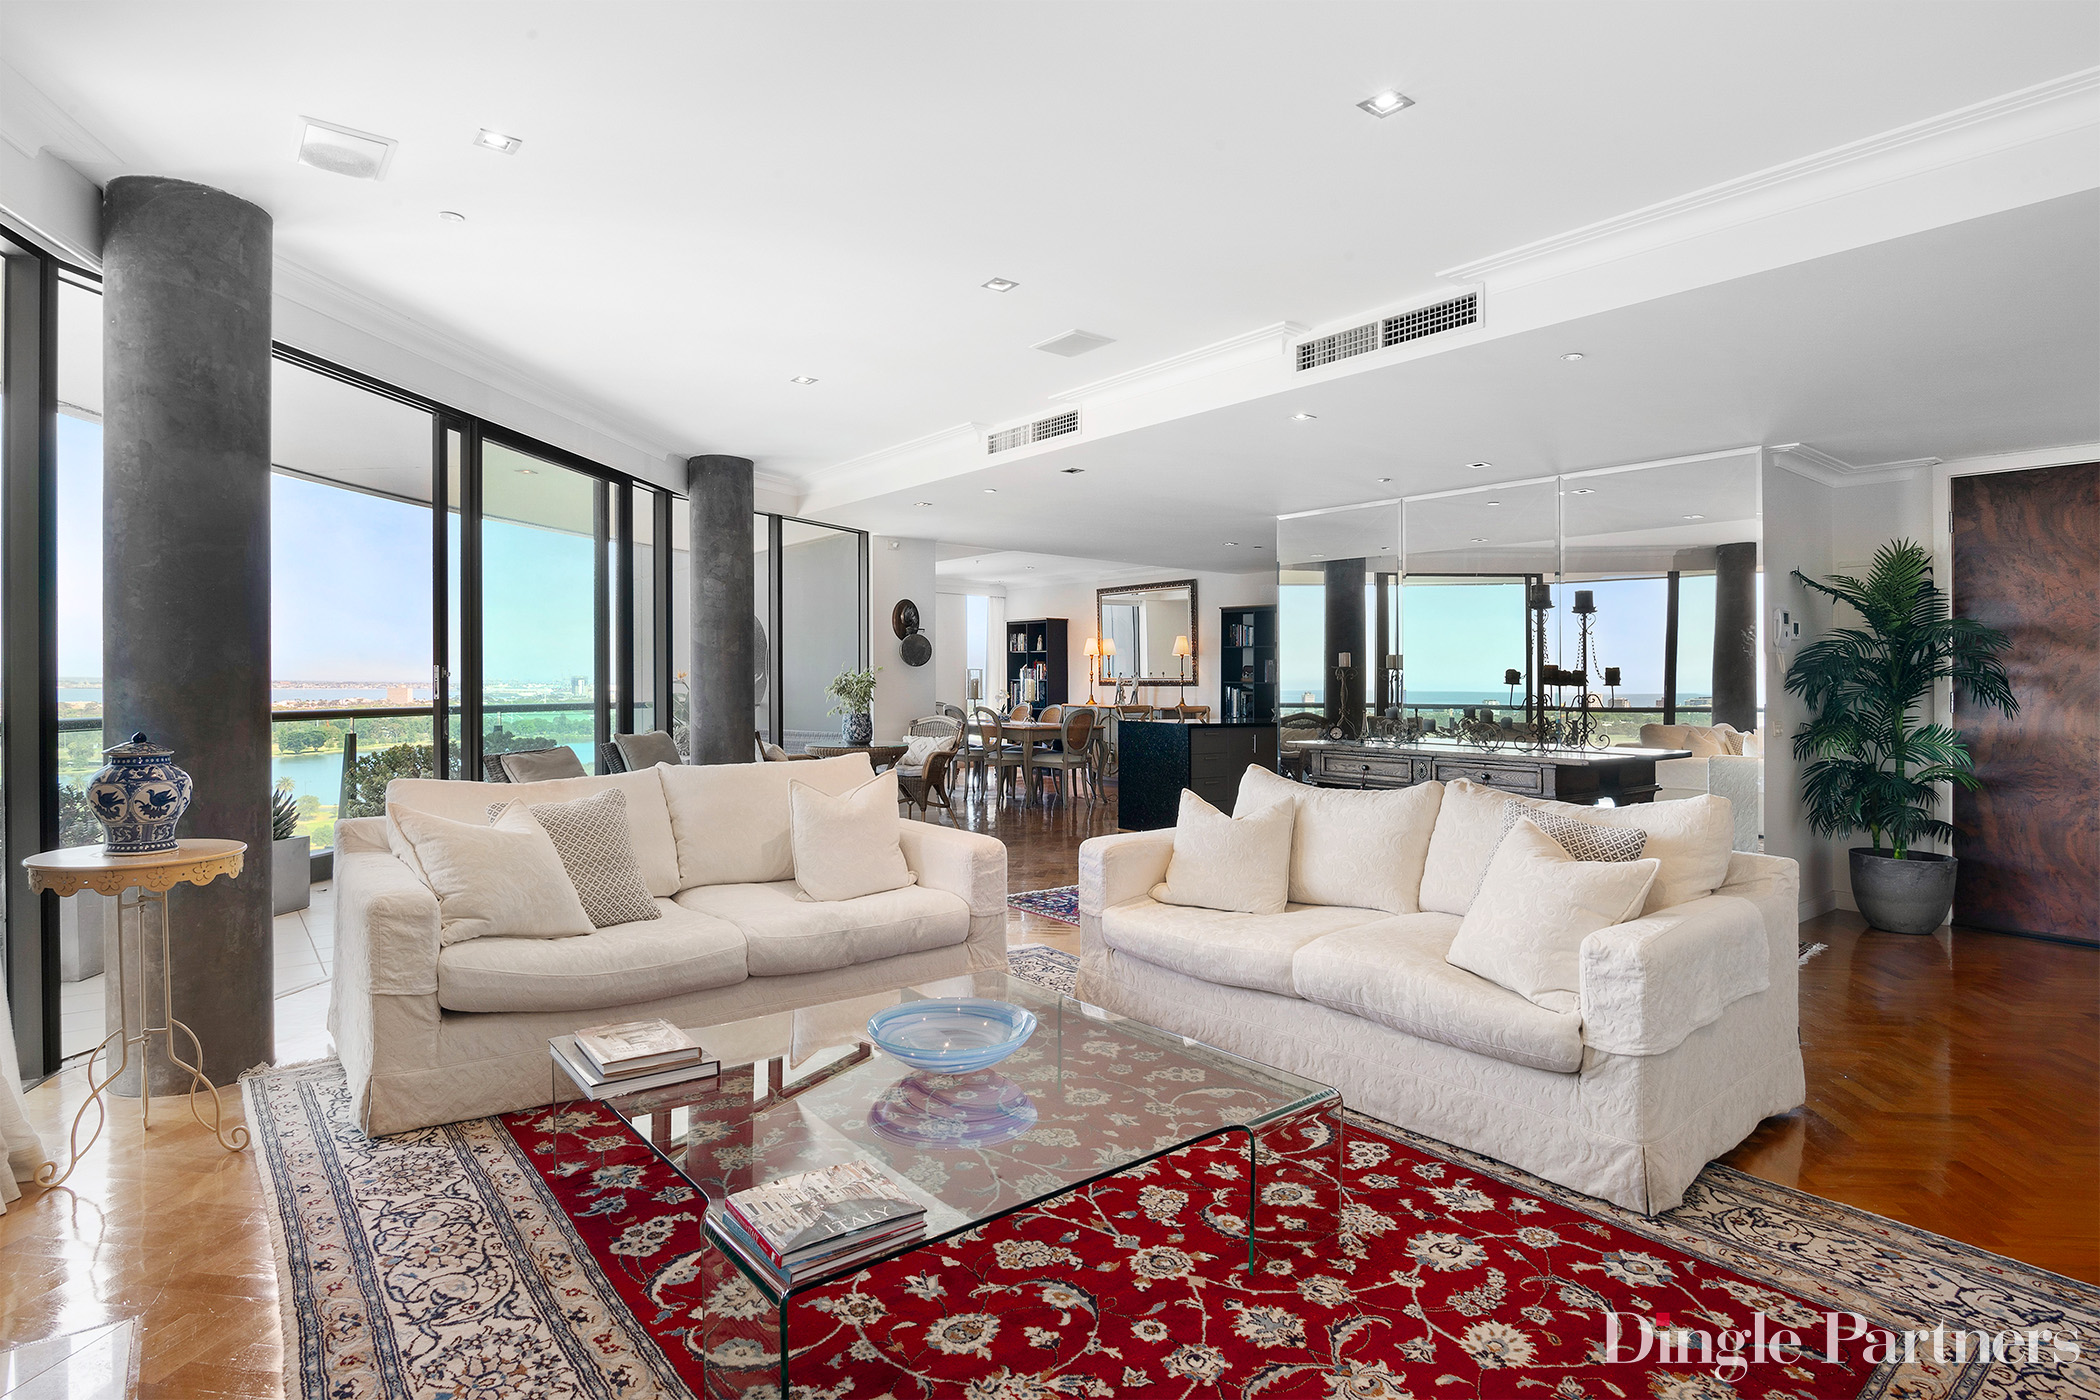
Well-located inner-city apartments — the stock that makes up the majority of Dingle Partners’ transaction activity across St Kilda Road, Carlton, Southbank, Richmond and the CBD — are not in the upper quartile of Melbourne’s housing market. They are, by price point, character and buyer pool, closer to the resilient mid-market segment that the data shows holding up considerably better than the headline correction figures suggest.
The unit-versus-house divergence is also directly relevant here. Nationally, units have demonstrated greater resilience throughout the downturn, supported by affordability and the concentration of buyer demand at more accessible price points. In Melbourne specifically, the gap between upper and lower value unit performance is narrower than the equivalent gap for houses — meaning the unit market is both more resilient and more uniform in its behaviour than the detached housing market facing the headlines.
This does not mean inner-city apartments are immune to the correction. It means they are experiencing a measured softening that reflects genuine affordability pressures, rather than the sharper premium correction that is driving the headline figures. For buyers and sellers in this segment, that distinction is worth understanding clearly.
What this tells us about the recovery
The same segmentation producing today’s correction sets up tomorrow’s recovery — and the shape of each segment’s recovery will be as distinct as the shape of its correction.
For the premium end, both drivers of the current fall need to unwind before values recover meaningfully. Borrowing capacity needs to improve, requiring rate cuts or sustained per capita growth, and strategic buyers waiting for a better entry need a signal that the bottom is in. All four major banks now expect the next cash rate move to be a cut, with CBA forecasting the earliest possible timing in May 2027 and ANZ the latest in September 2027 following holds at the upcoming meeting. When that signal arrives, the premium end carries considerable pent-up demand — the strategic waiters who have been sitting on the sidelines are not gone, they are watching. A sharp recovery at the top end is more plausible than a gradual one once the conditions are right.
For the resilient mid-market and unit segment, the recovery is likely to be steadier and earlier. The affordability cascade that has been supporting demand here does not reverse when rates fall — it simply concentrates demand further toward a segment that is already performing. Inner-city apartments in supply-constrained, high-yield precincts are well positioned to lead Melbourne’s value recovery, both because of their structural demand fundamentals and because their relative affordability means borrowing capacity improvements have an immediate and material effect on buyer access.
What this means for buyers
For buyers currently in the market, the segmentation is the most important piece of context to carry into negotiations. A property in the upper quartile of Melbourne’s detached housing market is in a different negotiating environment to a well-located inner-city apartment. In the former, you have meaningful leverage and the data supports a patient, disciplined approach. In the latter, the resilience of the segment means that your advantage is more modest, with values held up by accelerating rental incomes and a shortage of new supply at lower price points. The risk of waiting for a further correction is that you wait through the recovery instead, especially in Melbourne which has already “cooled off” longer than other capital cities.
For buyers considering moving down a tier from a property they can no longer afford — whether by choice or by necessity — the data is reasonably encouraging. The mid-market and unit segment is holding its value more consistently, which means what you’re buying into is more stable, even if what you’d like to buy has become temporarily out of reach.
What this means for sellers
For sellers, the first task is an honest assessment of which segment your property sits in — and that assessment should be based on your specific asset type, suburb and price point, not on the city-wide headline.
Sellers of premium detached houses face the most challenging conditions in the current market. The buyer pool has genuinely contracted at the top end, and the strategic waiters who would normally compete for premium stock are sitting on their hands. This means that pricing needs to reflect where the market is, not where it was. A realistic campaign with targeted marketing to the buyers most likely to move is worth considerably more than an aspirational price that sits empty on a market with a growing number of listing and higher average days on market.
Sellers of well-located inner-city apartments are in a meaningfully better position. The segment is more resilient, the buyer pool is broader — spanning owner-occupiers, investors and downsizers — and the rental evidence surrounding well-presented apartments in high-demand precincts provides an income floor that supports price. Accurate pricing remains essential, but the conversation with the market starts from a stronger base.
Frequently asked questions
Why are high-end Melbourne homes falling more than cheaper properties?
Two forces are operating simultaneously. The primary driver is the affordability cascade: rate rises reduce borrowing capacity most sharply in dollar terms at higher price points, redirecting buyers who can no longer afford premium properties toward the mid-market rather than out of the market entirely. The secondary driver is strategic waiting — discretionary buyers at the premium end can afford to delay in a way that most buyers cannot, suppressing demand further. Together these forces have produced a 10.5% fall from peak for upper-quartile Melbourne homes against less than 4% for the lower quartile.
Are Melbourne apartments affected by the same correction as houses?
Units are experiencing the same correction but to a considerably lesser degree. Nationally, units have proven more resilient throughout the downturn, supported by relative affordability and lower entry price points. In Melbourne specifically, the gap between upper and lower value unit performance is narrower than the equivalent gap in the detached housing market. Well-located inner-city apartments in established suburbs are among the most resilient segments in Melbourne’s current market.
When will Melbourne’s premium property market recover?
Recovery at the premium end requires both rate cuts to restore borrowing capacity and a clear signal that the bottom is in — to bring strategic buyers off the sidelines. All four major banks now expect the next cash rate move to be a cut, with the earliest forecasts pointing to mid-2027. When that signal arrives, the premium end is likely to recover sharply given the volume of pent-up demand that has been accumulating. The mid-market and unit segment is likely to recover earlier and more steadily.
What is the current median price for high-end Melbourne homes?
According to Cotality’s September 2026 data, upper-quartile Melbourne homes have a current median of approximately $1.2 million — down 10.5% from peak. Melbourne’s overall median dwelling value sits at approximately $786,718, with houses at $920,432 and units at $629,054.
Is now a good time to buy an inner-city Melbourne apartment?
For buyers who are finance-ready and focused on the right property, the current environment offers genuine advantages — reduced competition, more stock than a year ago, and realistic seller pricing in a segment that has proven more resilient than the headline correction suggests. The mid-market and unit segment is likely to lead Melbourne’s recovery when rate cuts arrive, meaning the entry point available today may look considerably more attractive in 18 to 24 months.
Should I sell my Melbourne property now or wait for the market to recover?
The answer depends significantly on which segment your property sits in. Sellers of premium detached houses face the most challenging conditions and need to price realistically to find their buyer. Sellers of well-located inner-city apartments are in a stronger relative position, with a broader buyer pool and more resilient segment fundamentals. In either case, the answer is less about timing the market and more about the quality of the campaign — pricing, presentation and reaching the right buyer pool for your specific asset.
Dingle Partners has been operating in Melbourne’s inner-city property market since 1973. Our team across six inner-city offices — spanning St Kilda Road, Carlton, Richmond, Southbank, Docklands and the CBD — monitors these conditions daily. If you’d like to understand where your specific property sits in the current market, we’d welcome the conversation.
Get in touch with one of our experienced agents from across our office network; or request your obligation free market and property report today.